Positives in November
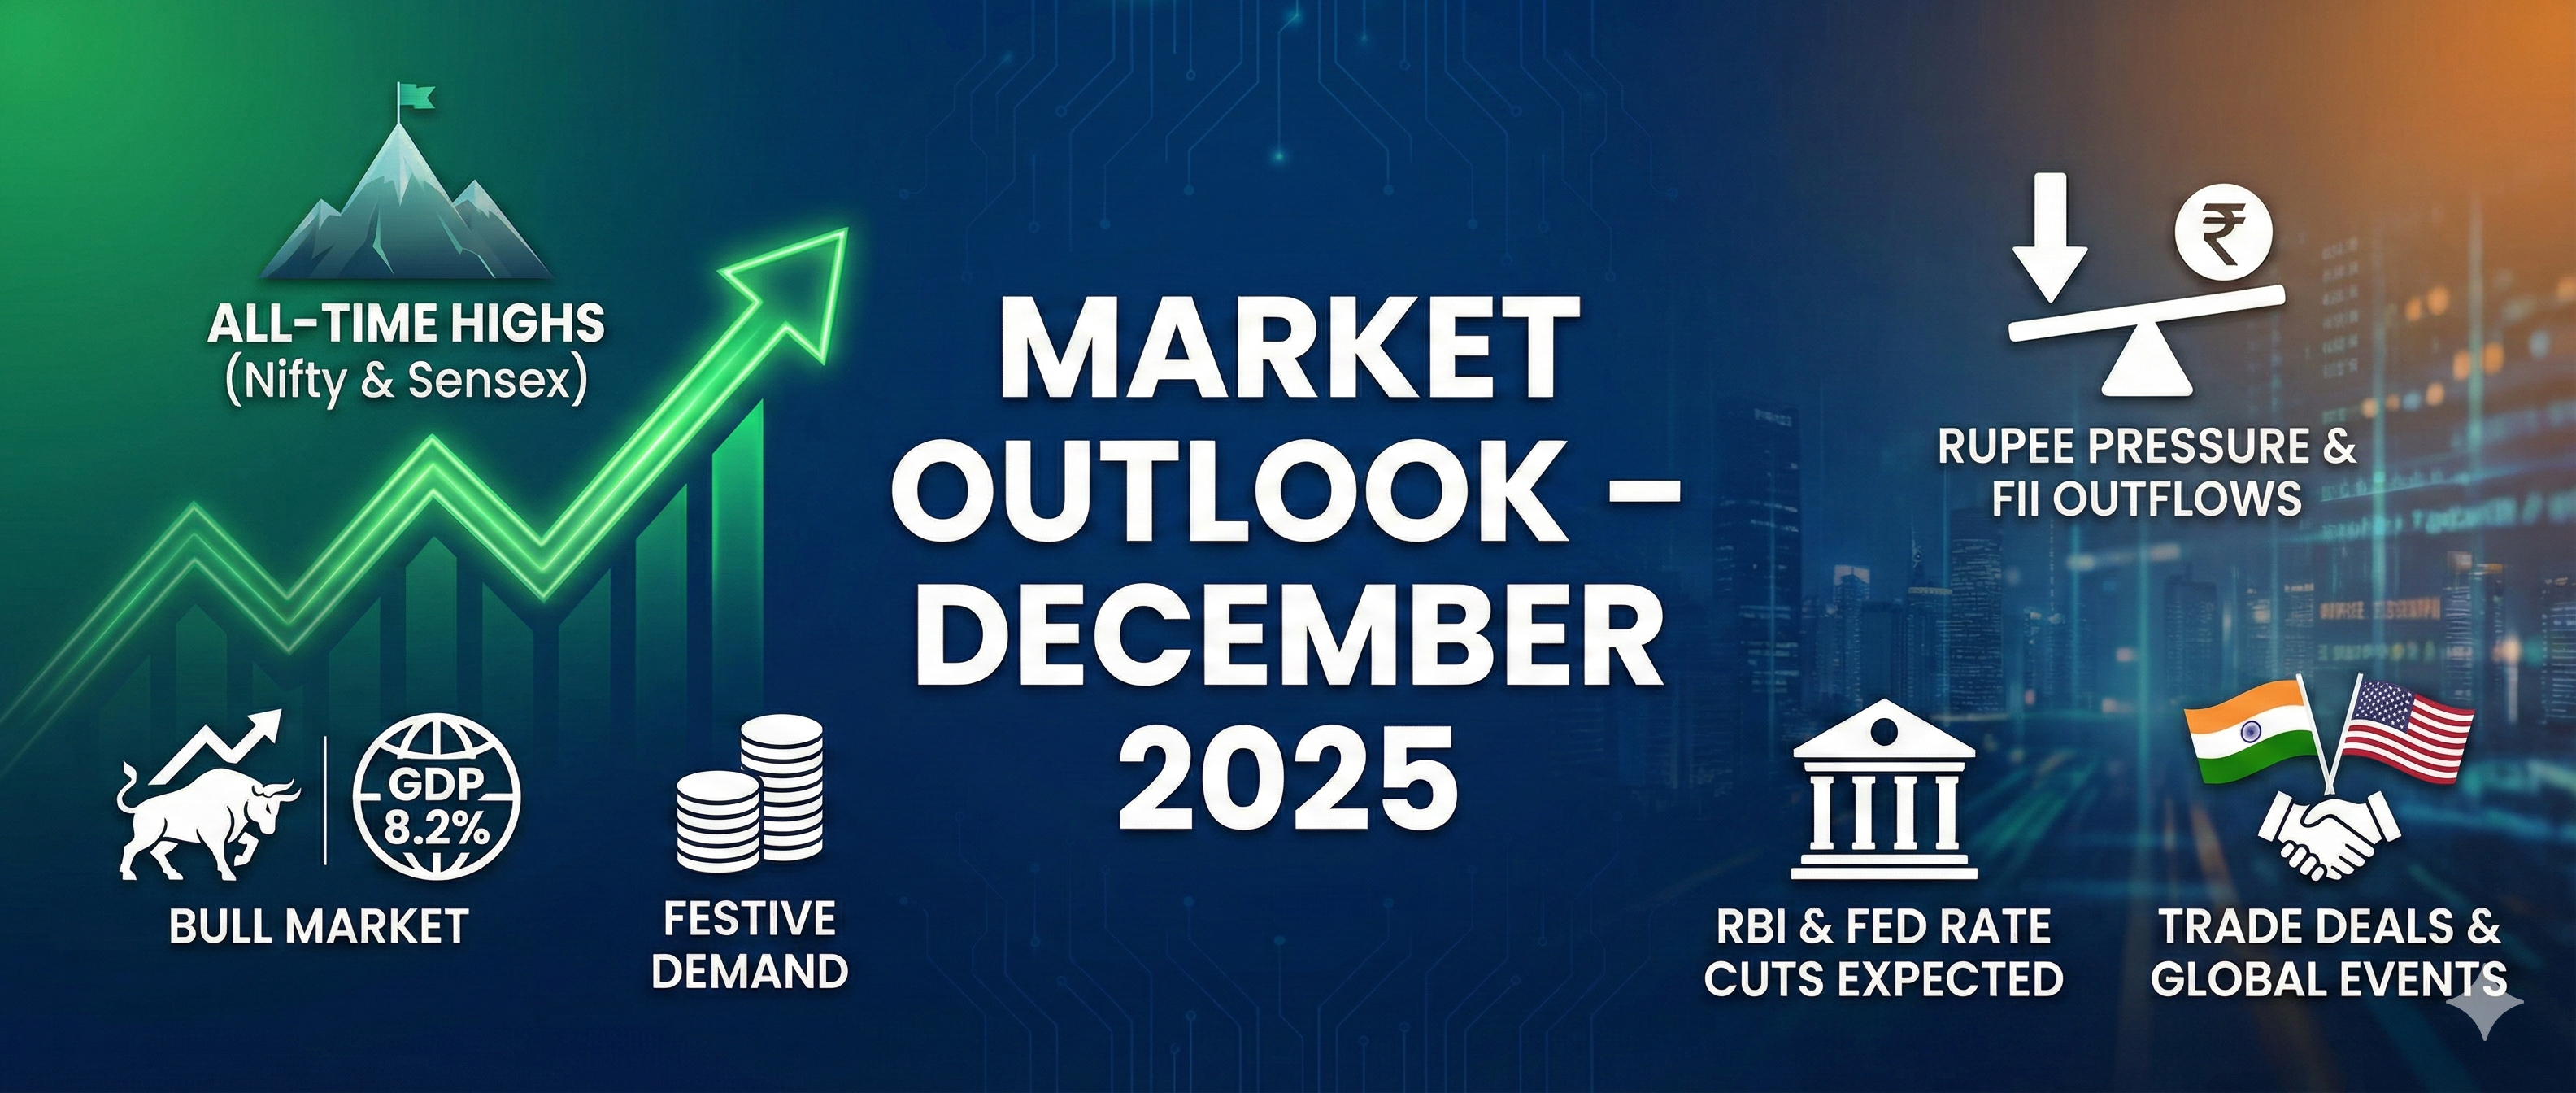
- Nifty & Sensex touched all time high of 26,310 & 86,055
respectively after remaining rangebound for more than a year. - India’s economy grew 8.2% YoY in Q2 FY26, the fastest pace in six
quarters — easily beating consensus forecasts and last year’s 5.6%. - Donald Trump’s stance on tariffs toward India has become more
conciliatory. With ongoing trade negotiations and India’s recent reduction in
oil purchases from Russia, a positive announcement may be expected soon. - GST Collections – November ₹1.70 lakh crore Marginal 0.7% YoY rise, with
import GST up 10.2% but domestic GST down 2.3%. Year-to-date growth remains
strong at 8.9%. - Markets rebound in November was also aided by the resolution of the US
government shutdown, better-than-expected Q2 earnings, softer inflation, and a
strong NDA mandate in Bihar. - Oil prices remained low, trading in a range of 58-60$ per barrel.
- Festive demand & GST cut boosted urban & rural consumption sales
growth. Auto Sales –2W & CV Sales were up – Avrage 30%. - Globally, financial conditions eased after the Fed’s 25 bps October cut,
with a possible additional cut in December.
Negatives in November
- The rupee dropped to a fresh record low (around ₹89.49 per US dollar) in
Nov, weighed down by weak foreign investment inflows, uncertainty over global
trade deals, and broad currency pressure. - Manufacturing slump, export-linked industries hurt by tariffs &
global headwinds. India Manufacturing Purchasing Managers’ Index (PMI) fell
from 59.2 in October to 56.6 in Nov, highlighting the slowest improvement in
operating conditions since Feb. - FIIs were again net sellers in Indian Equity market with outflow of
17.5K crores.
December Key Events
- RBI Monetary Policy – 5th Dec. Rate cut expected from RBI
as inflation has eased considerably. Positive for Markets. - Russian President Putin visits India – 4-5th Dec. Key defence deals expected
to be signed. Positive for Markets. - Fed Interest Rate Dec – 11th Dec, expected to cut rates by
25bps. Positive for Markets.
Investment Strategy & Asset Allocation
- Nifty range 25,500-26,500; downside limited, new highs expected.
- Markets expected to rise cautiously. US trade deal is the major
announcement markets are waiting for and will not make any big moves unless it
is announced. - Q3 FY26 earnings will shape market directions going ahead, expected to
be higher nos. boosting equity markets. - Globally, US economic nos. are in line. Solid Nvidia results calmed the
markets on AI bubble theory. - Japan inflation nos. needs to be tracked. With appointment of pro-rate
hike Prime Minister Sanae Takaichi, any interest rate hikes in future will push
outflow from global markets triggering global volatility.